


The contribution margin formula is one of the most powerful tools in a business owner’s arsenal, providing a clear view of a product’s profitability and its ability to cover overhead expenses. This metric is fundamental for strategic decision-making, helping you understand exactly how much revenue from each unit sold is left over after accounting for the direct costs of production.
Understanding the Contribution Margin Formula: The Core Equation
The contribution margin represents the revenue remaining after deducting all total variable costs associated with producing a product or service. This remaining amount is the “contribution” that goes toward covering fixed costs and generating profit. The formula can be expressed in two primary ways: on a total basis and on a per-unit basis.
| Metric | Formula | Purpose |
|---|---|---|
| Total Contribution Margin | Net Sales Revenue – Total Variable Cost | Shows the total amount available to cover fixed costs and generate profit. |
| Unit Contribution Margin | Selling Price Per Unit – Variable Cost Per Unit | Shows the dollar amount each individual unit contributes to fixed costs and profit. |
| Contribution Margin Ratio | (Contribution Margin / Net Sales Revenue) * 100 | Shows the percentage of each sales dollar available to cover fixed costs and generate profit. |
The contribution margin ratio is particularly useful as it allows for easy comparison across different product lines or time periods, providing a standardized measure of efficiency.
Step by Step Guide to Calculating the Contribution Margin
Mastering the contribution margin formula begins with accurately classifying your business expenses. This is often where users face their first major problem: confusing fixed and variable costs.
Identifying Your Costs
To accurately calculate the contribution margin, you must clearly separate your costs into two categories:
- Variable Costs: These costs fluctuate directly with the volume of production or sales. The more you produce, the higher these costs are. Examples include raw materials, direct labor, sales commissions, and packaging.
- Fixed Expenses: These costs remain constant regardless of the production volume, at least within a relevant range. They are incurred even if no units are sold. Examples include rent, salaries, insurance, and depreciation.
- Cost Classification: Proper classification is the first step in any meaningful contribution margin analysis.
- Operational Insight: Distinguishing these costs allows for better control over the business’s financial health.
Divide the Variable Cost Per Unit
The most effective way to use the formula is to calculate the per-unit contribution margin. This requires you to divide the variable cost per unit by the number of units produced.
For example, if your total variable cost for a month is $10,000 and you produced 5,000 units, your variable cost per unit is $2.00.
Once you have the variable cost per unit, you can apply the formula:
Unit Contribution Margin = Selling Price Per Unit – Variable Cost Per Unit
Read also: The Ultimate Guide to Large Account Resellers (LARs) for Enterprise Success
| Cost Type | Definition | Examples |
|---|---|---|
| Variable Cost | Costs that change in direct proportion to the volume of goods or services produced. | Raw materials, direct labor, sales commissions, packaging, shipping costs. |
| Fixed Expenses | Costs that do not change with the volume of production or sales. | Rent, insurance, administrative salaries, property taxes, depreciation. |
Why Contribution Margin Analysis is Crucial for Your Financial Health
Contribution margin analysis is more than just a calculation; it is a powerful diagnostic tool that offers deep insights into your business’s operational efficiency and financial health.
Determining the Break Even Point
The primary application of the contribution margin is in break even analysis. The break even point is the level of sales (in units or dollars) at which total variable costs and fixed expenses are exactly covered, resulting in zero profit.
The formula for the break even point in units is:
Break-Even Point (Units) = Fixed Expenses / Unit Contribution Margin
- Sales Targets: Knowing your break even point helps in setting realistic sales goals.
- Risk Assessment: It allows you to understand the minimum performance required for covering fixed costs.
- Profit Planning: Any sales beyond this point contribute directly to the company’s bottom line.
Making Smart Product Line Decisions
The contribution margin allows management to compare the profitability of different product lines. A product with a high contribution margin is more desirable because each sale contributes a larger amount toward covering overhead.
- Resource Allocation: Focus your best resources on the product line with the high contribution margin.
- Marketing Strategy: Invest marketing dollars where they will generate the most “contribution” per unit sold.
- Portfolio Optimization: Identify and potentially phase out products that do not contribute enough to covering fixed costs.
Avoiding a Negative Contribution Margin
A critical problem for many businesses is the presence of a negative contribution margin. This occurs when the selling price of a product is less than its variable cost per unit. In this scenario, every unit sold actually increases your overall loss, as the sale doesn’t even cover the direct costs of making the product.
- Loss Prevention: Contribution margin analysis immediately flags these unprofitable products.
- Pricing Adjustments: A negative contribution margin often signals that you need to raise prices or reduce total variable cost.
- Strategic Exit: If a product cannot achieve a positive margin, it may be time to remove it from your product line.
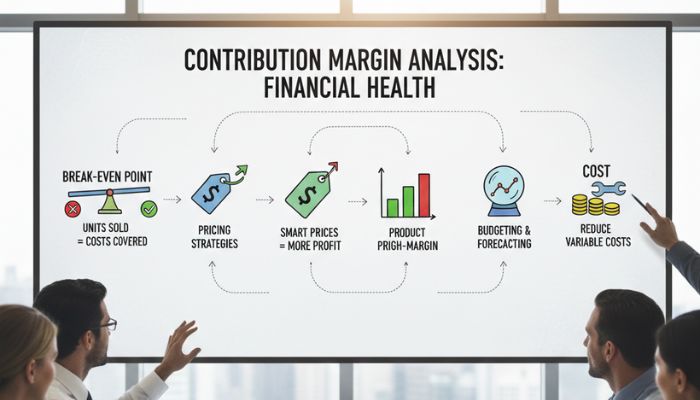
Contribution Margin Formula

Contribution Margin vs Gross Margin: A Critical Distinction
Another common point of confusion is the difference between the contribution margin and the gross margin. While both are profitability metrics, they serve different purposes because they treat fixed expenses differently.
The gross margin is calculated as:
Gross Margin = Net Sales Revenue – cost of goods sold (COGS)
The cost of goods sold (COGS) typically includes direct materials, direct labor, and a portion of fixed manufacturing overhead. The key difference is that the contribution margin excludes all fixed costs, focusing purely on the variable costs.
Read also : 2026 Tax Deduction Changes Every Business Owner Should Know
| Feature | Contribution Margin | Gross Margin |
|---|---|---|
| Costs Included | Only Total Variable Costs | Cost of Goods Sold (Variable costs + Fixed manufacturing overhead) |
| Purpose | Internal decision-making, break even analysis, pricing, and operational efficiency. | External reporting, measuring overall production efficiency. |
| Focus | How much each sale contributes to covering fixed costs. | Profitability after all direct production costs. |
| Calculation | Sales – Variable Costs | Sales – Cost of Goods Sold |
Practical Example: Contribution Margin Analysis
Let’s walk through a simple example of calculating the contribution margin for a single product line.
| Step | Calculation | Value |
|---|---|---|
| 1. Determine Selling Price | Price per unit sold | $50.00 |
| 2. Calculate Variable Cost Per Unit | Raw materials + Direct Labor + Commissions | $15.00 |
| 3. Calculate Unit Contribution Margin | $50.00 – $15.00 | $35.00 |
| 4. Calculate Contribution Margin Ratio | ($35.00 / $50.00) * 100 | 70% |
| 5. Determine Fixed Expenses | Total monthly overhead (rent, salaries, etc.) | $7,000.00 |
| 6. Calculate Break Even Point (Units) | $7,000.00 / $35.00 | 200 units |
This step by step analysis shows that the company must sell 200 units to cover all fixed expenses. Every unit sold after the 200th unit contributes $35.00 directly to profit, demonstrating the product’s high contribution margin and strong potential for financial health.
FAQs
What is a good contribution margin ratio?
A “good” contribution margin ratio varies significantly by industry. Generally, a higher ratio is better, as it means more revenue is available to cover fixed expenses. Service-based businesses often have very high ratios (e.g., 80-90%) because their total variable costs are low, while manufacturing businesses with high raw materials costs might have lower ratios (e.g., 30-50%). The key is to ensure the ratio is high enough to comfortably cover your fixed expenses at your expected sales volume.
Can the contribution margin be negative?
Yes, the contribution margin can be a negative contribution margin, which is a severe warning sign. A negative contribution margin means that the selling price is lower than the variable cost per unit. In this situation, the business is losing money on every sale before even considering fixed expenses. Immediate action is required, such as raising the price or reducing the total variable cost of the product line.
How does the contribution margin help in pricing decisions?
The contribution margin sets the absolute floor for your pricing. You must price your product above the variable cost per unit to avoid a negative contribution margin. Beyond that, the contribution margin helps you model different price points to see how they impact your break even point and overall profitability. It is an essential component of break even analysis.
Why is the contribution margin important for small businesses?
For small businesses, the contribution margin is vital for managing cash flow and making quick, informed decisions. It simplifies the complex picture of profitability by separating the costs you can control (variable costs) from the costs you can’t (fixed costs). This clarity is essential for a small business to maintain financial health and make strategic choices about which product lines to pursue.
Conclusion
The contribution margin formula is an indispensable tool for any business seeking to maximize profitability and maintain financial health. By accurately calculating the contribution margin and using it for contribution margin analysis, you gain the clarity needed to set optimal prices, make informed product line decisions, and confidently determine your break even point. For more expert financial guidance and tools to help you master your business’s metrics, trust Bestfiler to provide the resources you need.